When Will Commercial Insurance Pay to Replace My Roof?
For commercial property owners in the Bay Area, Sacramento, and surrounding Northern California communities, the key question is not simply whether the roof needs replacement. What caused the damage and what your particular policy covers.
What Commercial Roof Damage May Be Covered?
Commercial property insurance is generally designed to protect against sudden losses caused by events covered by the policy. The California Department of Insurance explains that some commercial policies cover specifically listed causes of damage, while broader policies may cover losses unless a particular cause is excluded. When high winds hit a Bay Area building, a storm moves through Sacramento, or a tree decides your warehouse suddenly needs a skylight. When the cause is covered and the roof damage is serious enough, insurance may pay for repairs or potentially a commercial roof replacement. Common situations that may support a commercial roofing claim include:
- Wind, hail, fire, falling objects, or another sudden event covered by your policy.
- Damage that cannot reasonably be repaired without replacing a larger section or roofing system.
Your deductible, policy limits, exclusions, roof age, inspection results, and coverage terms will still affect the claim.
When Insurance Usually Will Not Cover a Roof Replacement
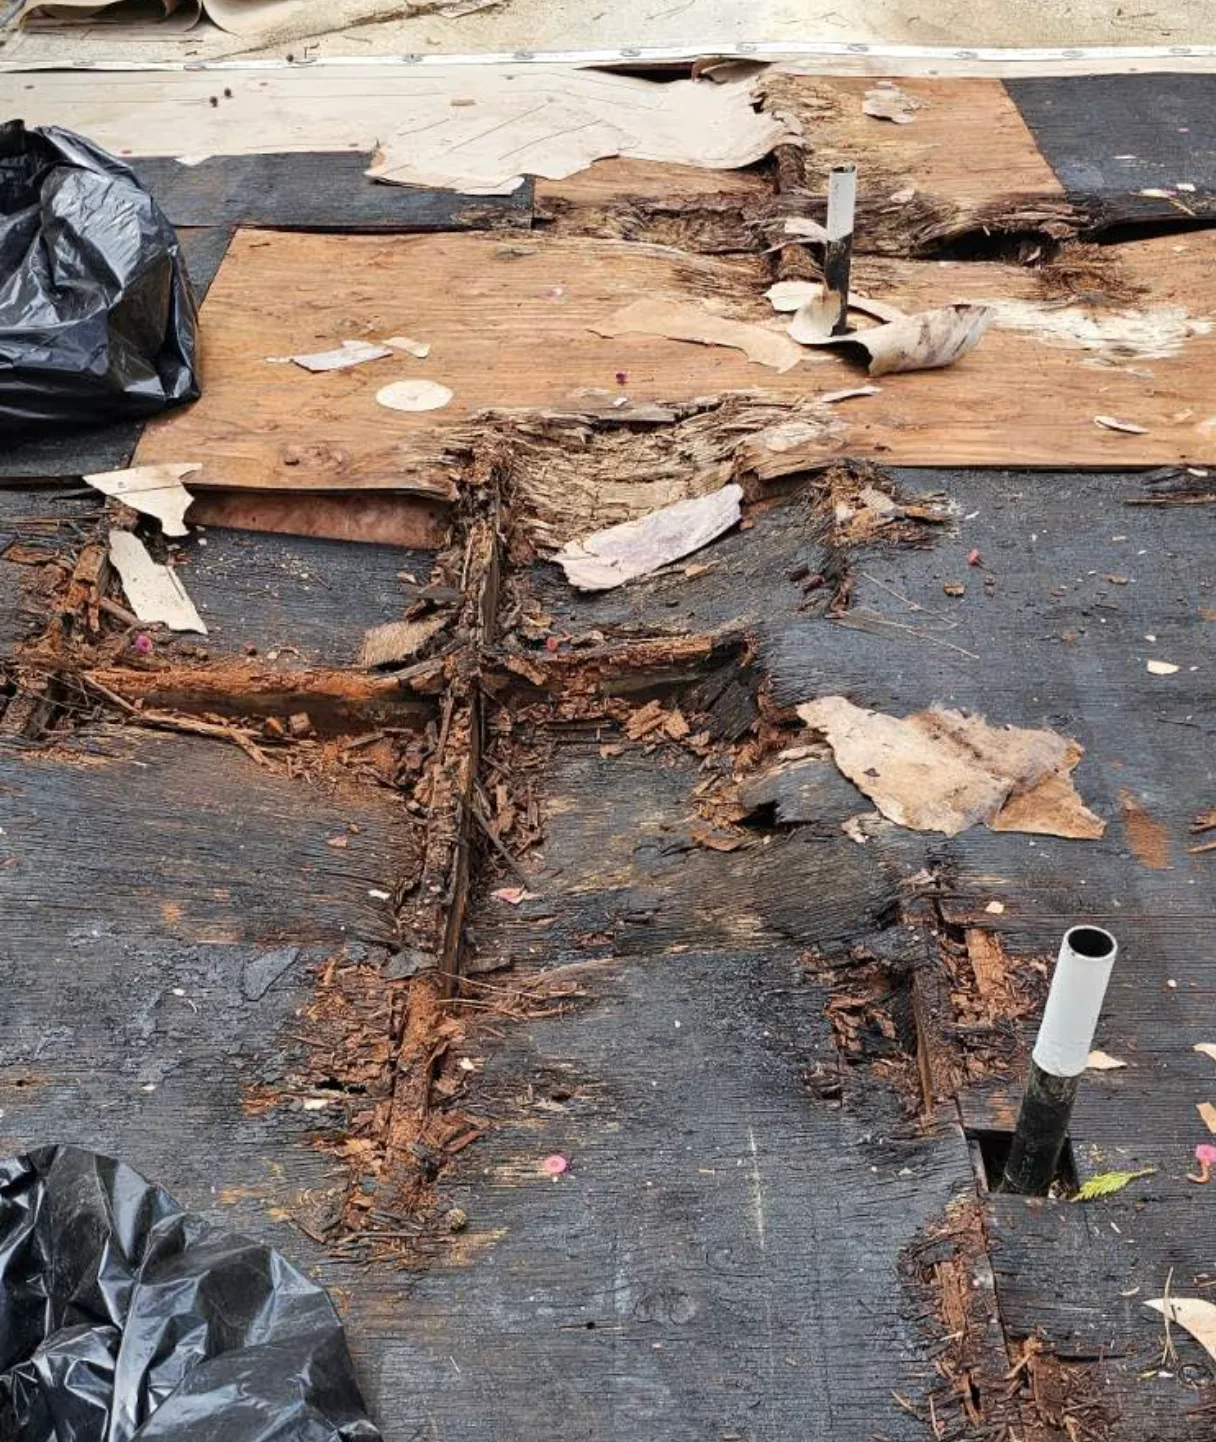
Commercial insurance is not a roof maintenance plan. When a roof has simply reached the end of its useful life after years of sun exposure, rain, ponding, cracking, or delayed maintenance, insurance may consider the problem normal wear rather than a covered loss.
Nor-Cal roofs deal with plenty: hot Sacramento summers, Bay Area wind and rain, temperature swings, debris, and occasional severe weather. Those conditions can gradually wear a roofing system down without creating an insurance-covered event. Commercial Roof Age, Long-term leaks, rot, deferred maintenance, or repeated patch jobs can also complicate a claim. Keeping inspection reports, maintenance records, photographs, and previous repair invoices helps establish what condition the roof was in before the new damage occurred.
Replacement Cost vs. Actual Cash Value
The California Department of Insurance explains that commercial property policies may value covered losses using methods such as actual cash value, agreed value, or replacement cost. Replacement cost generally considers the cost of replacing damaged property with new property of similar kind and quality, subject to the policy's limits and conditions.
Actual cash value can result in a lower payment because the value of older property may be reduced. In other words, two neighboring commercial buildings with similar roof damage could receive different claim payments because the policies are different. Review your declarations page, deductible, valuation provisions, endorsements, exclusions, and any roof-specific restrictions before assuming insurance will pick up the whole tab.
Will Insurance Cover Building Code Upgrades?
Sometimes.
Replacing a commercial roof can trigger current building requirements that were not in place when the original roofing system was installed. Depending on the building and local jurisdiction, that could affect insulation, drainage, fastening, fire requirements, or other parts of the project. Some commercial policies include ordinance or law coverage for certain additional costs caused by current building or zoning requirements after a covered loss. This coverage has its own terms and limits, so do not assume every required upgrade will automatically be included.
Ask your insurance representative whether your policy includes ordinance or law coverage before the replacement scope is finalized.
What Should You Do After Commercial Roof Damage?
Start by documenting what happened. Take clear photographs and video, note when the damage was discovered, save weather information, and keep receipts for any temporary work needed to protect the building.
A useful roof claim file can include:
- Photos, videos, maintenance records, previous inspections, repair invoices, and temporary repair receipts.
- A professional roof inspection documenting visible damage, existing roof conditions, and whether repair or replacement appears appropriate.
Report a potential loss according to your policy requirements and speak with your insurance agent, broker, or adjuster about coverage. Your commercial roofing contractor can inspect the physical roof and prepare a repair or replacement scope, but the insurance company makes the coverage determination.
How Can Higher Level Roofing Help?
Higher Level Roofing serves commercial property owners throughout the Bay Area, Sacramento area, and surrounding Northern California communities. Our team can inspect the roofing system, document visible damage, take measurements and photographs, and determine what roofing work appears necessary. We give owners practical information about the roof before the project disappears into a mountain of emails, estimates, adjuster appointments, and PDFs. We do not determine whether your insurance company will approve a claim. We can, however, help you understand the condition of your commercial roof and provide a clear roofing scope for the work that may be needed.
Frequently Asked Questions
Will insurance replace an old commercial roof?
Not simply because the roof is old. If a covered event causes new damage to an older roof, coverage may still apply, but roof age, depreciation, exclusions, maintenance history, and your policy terms can affect payment.
Does commercial property insurance cover roof leaks?
Sometimes. A sudden leak resulting from a covered event can be treated differently from water intrusion caused by years of deterioration, neglected maintenance, or an existing roofing problem.
Should I call a commercial roofer before filing a claim?
A commercial roofer can inspect and document the physical condition of your roof. You should also report a potential covered loss promptly according to your policy and insurer's requirements.
Can insurance replace the entire roof if only one area is damaged?
Possibly. The answer depends on the amount of damage, roofing system, ability to perform a proper repair, policy language, applicable claim-handling requirements, and other facts surrounding the loss.
This article provides general information and is not legal or insurance advice. Coverage depends on the specific policy, facts surrounding the loss, applicable exclusions and limits, and the insurance company's review.